You Signed the Settlement. The Damage Kept Spreading: Now What?
Whether a public adjuster can help reopen a closed insurance claim depends on your insurance policy, the reason the claim was closed, state regulations and whether new or previously undiscovered covered damage has been found. A public adjuster cannot automatically reopen every claim but they may be able to review your situation and explain what options are available.
A storm damaged your roof.
The insurance company inspected the property, sent a payment, and you thought the claim was over.
A few weeks later, your contractor removed the shingles and found soaked decking underneath. Or maybe the drywall came down after a pipe burst, revealing mold inside the walls.
Now you're asking the question thousands of homeowners search for every year:
Can a public adjuster reopen a closed insurance claim?
The answer isn't always a simple yes or no.
At TSO Adjustment Service, we've spoken with many homeowners who believed they had missed their chance to recover additional covered damage. In some situations, that isn't necessarily the end of the story.
Here's what you should know before assuming your claim is permanently closed.
Why Homeowners Ask This Question More Than Ever
Many types of property damage don't reveal their full extent immediately.
For example-
- Water may stay trapped behind drywall.
- Roof damage may not be visible until repairs begin.
- Smoke damage may spread through HVAC systems.
- Structural issues may only appear after debris is removed.
Because of this, homeowners discover additional damage after accepting an insurance settlement.
That leads to one important question:
Can a public adjuster reopen a closed insurance claim if new problems appear?
The answer depends on several factors.
First, What Does "Closed Claim" Actually Mean?
Many homeowners believe "closed" means nothing else can ever happen.
That's not always true.
A claim may be closed because-
- Payment has been issued.
- Repairs were expected to begin.
- The insurance company believes the claim is complete.
- Required paperwork has been finished.
In some cases, additional information may still be submitted if the policy and claim circumstances allow it.
Situations Where Additional Review May Be Possible
Every policy is different but homeowners sometimes discover information that wasn't available during the original inspection.
Examples include-
Hidden Water Damage
Water travels behind walls, under flooring or into insulation. The full damage may not become visible until demolition starts.
Structural Damage
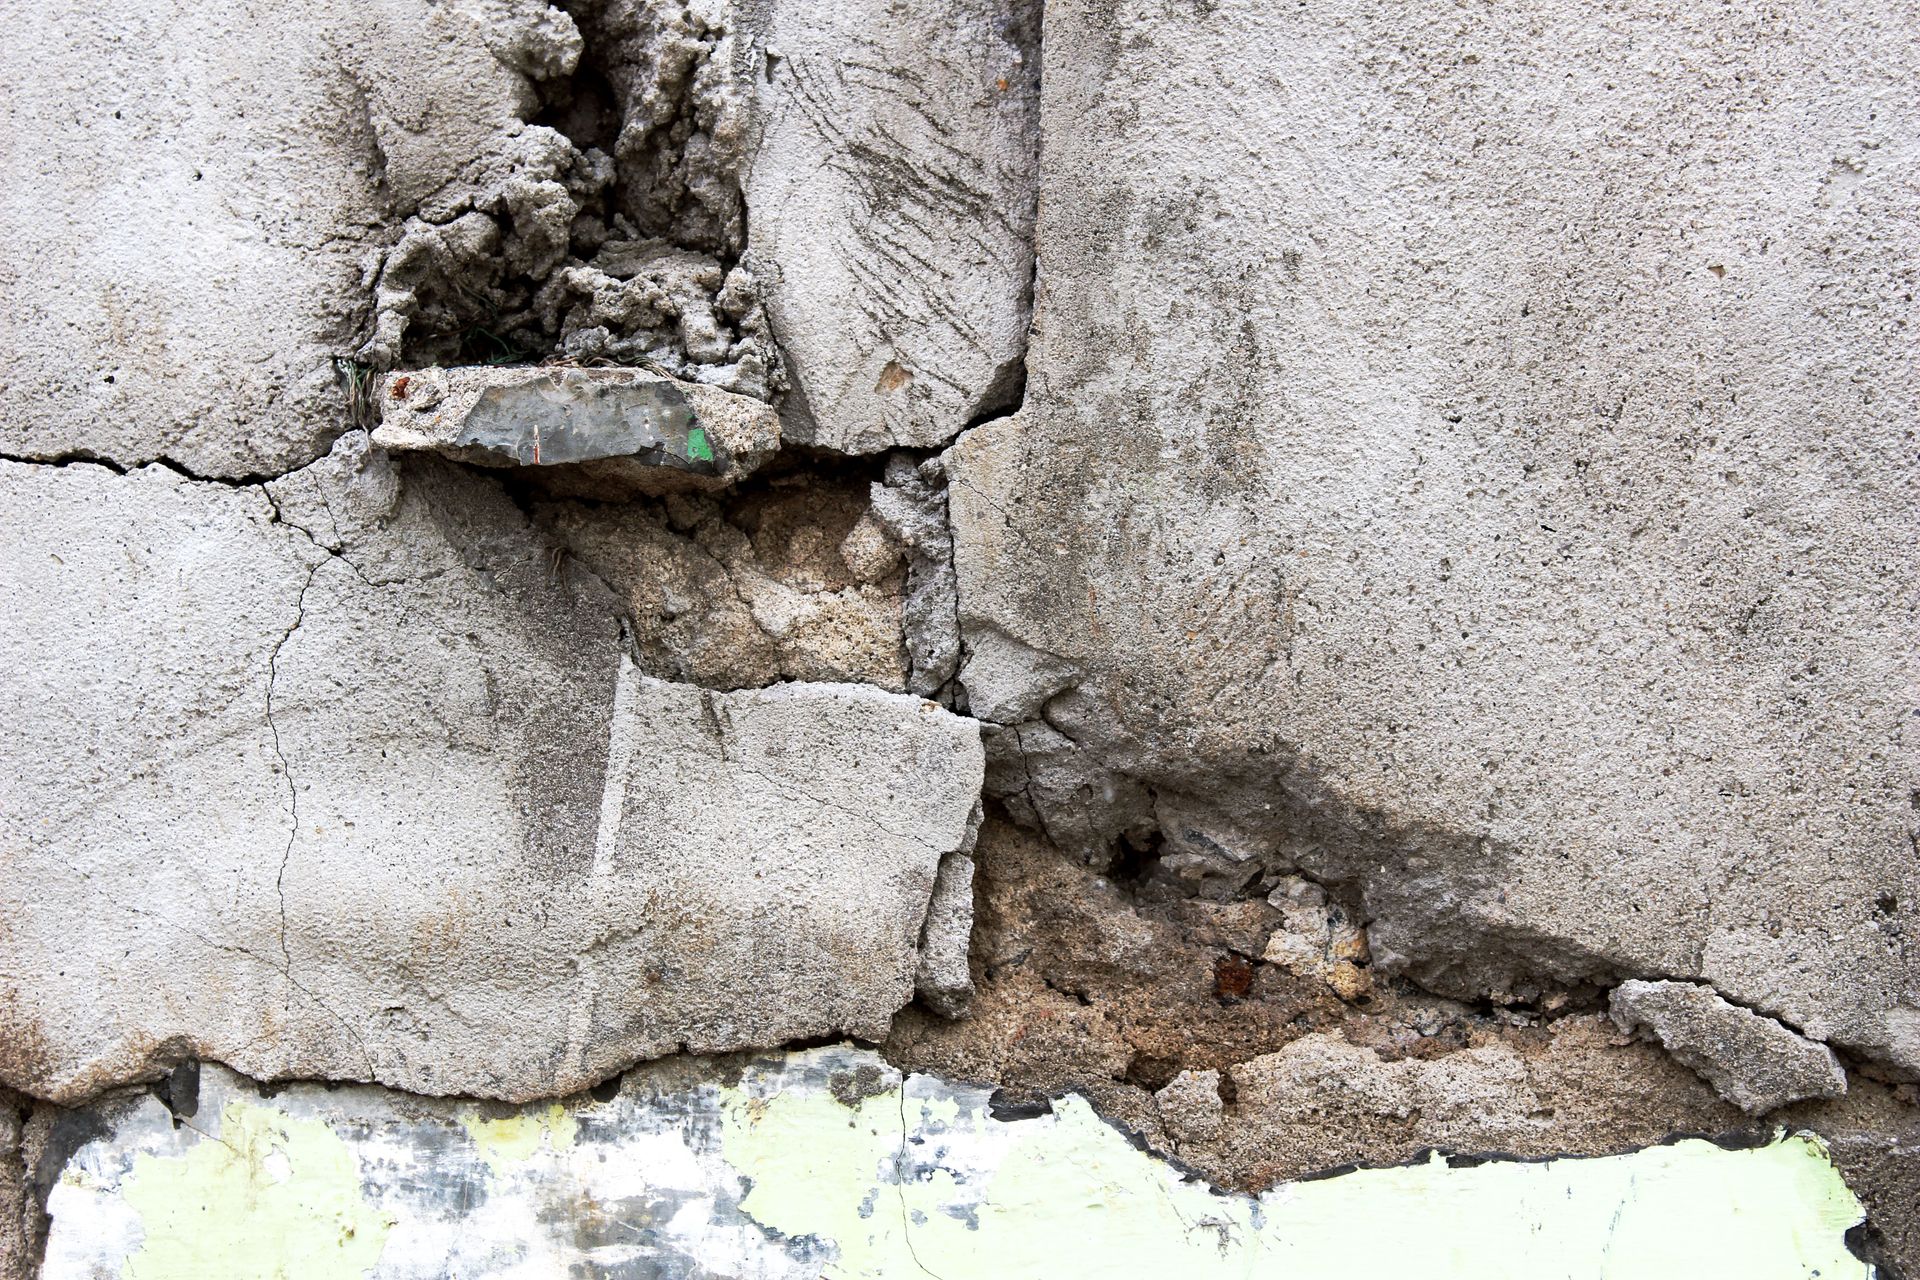
A roof may appear repairable from the outside. Once contractors begin work, damaged decking or framing may be uncovered.
Smoke or Fire Damage
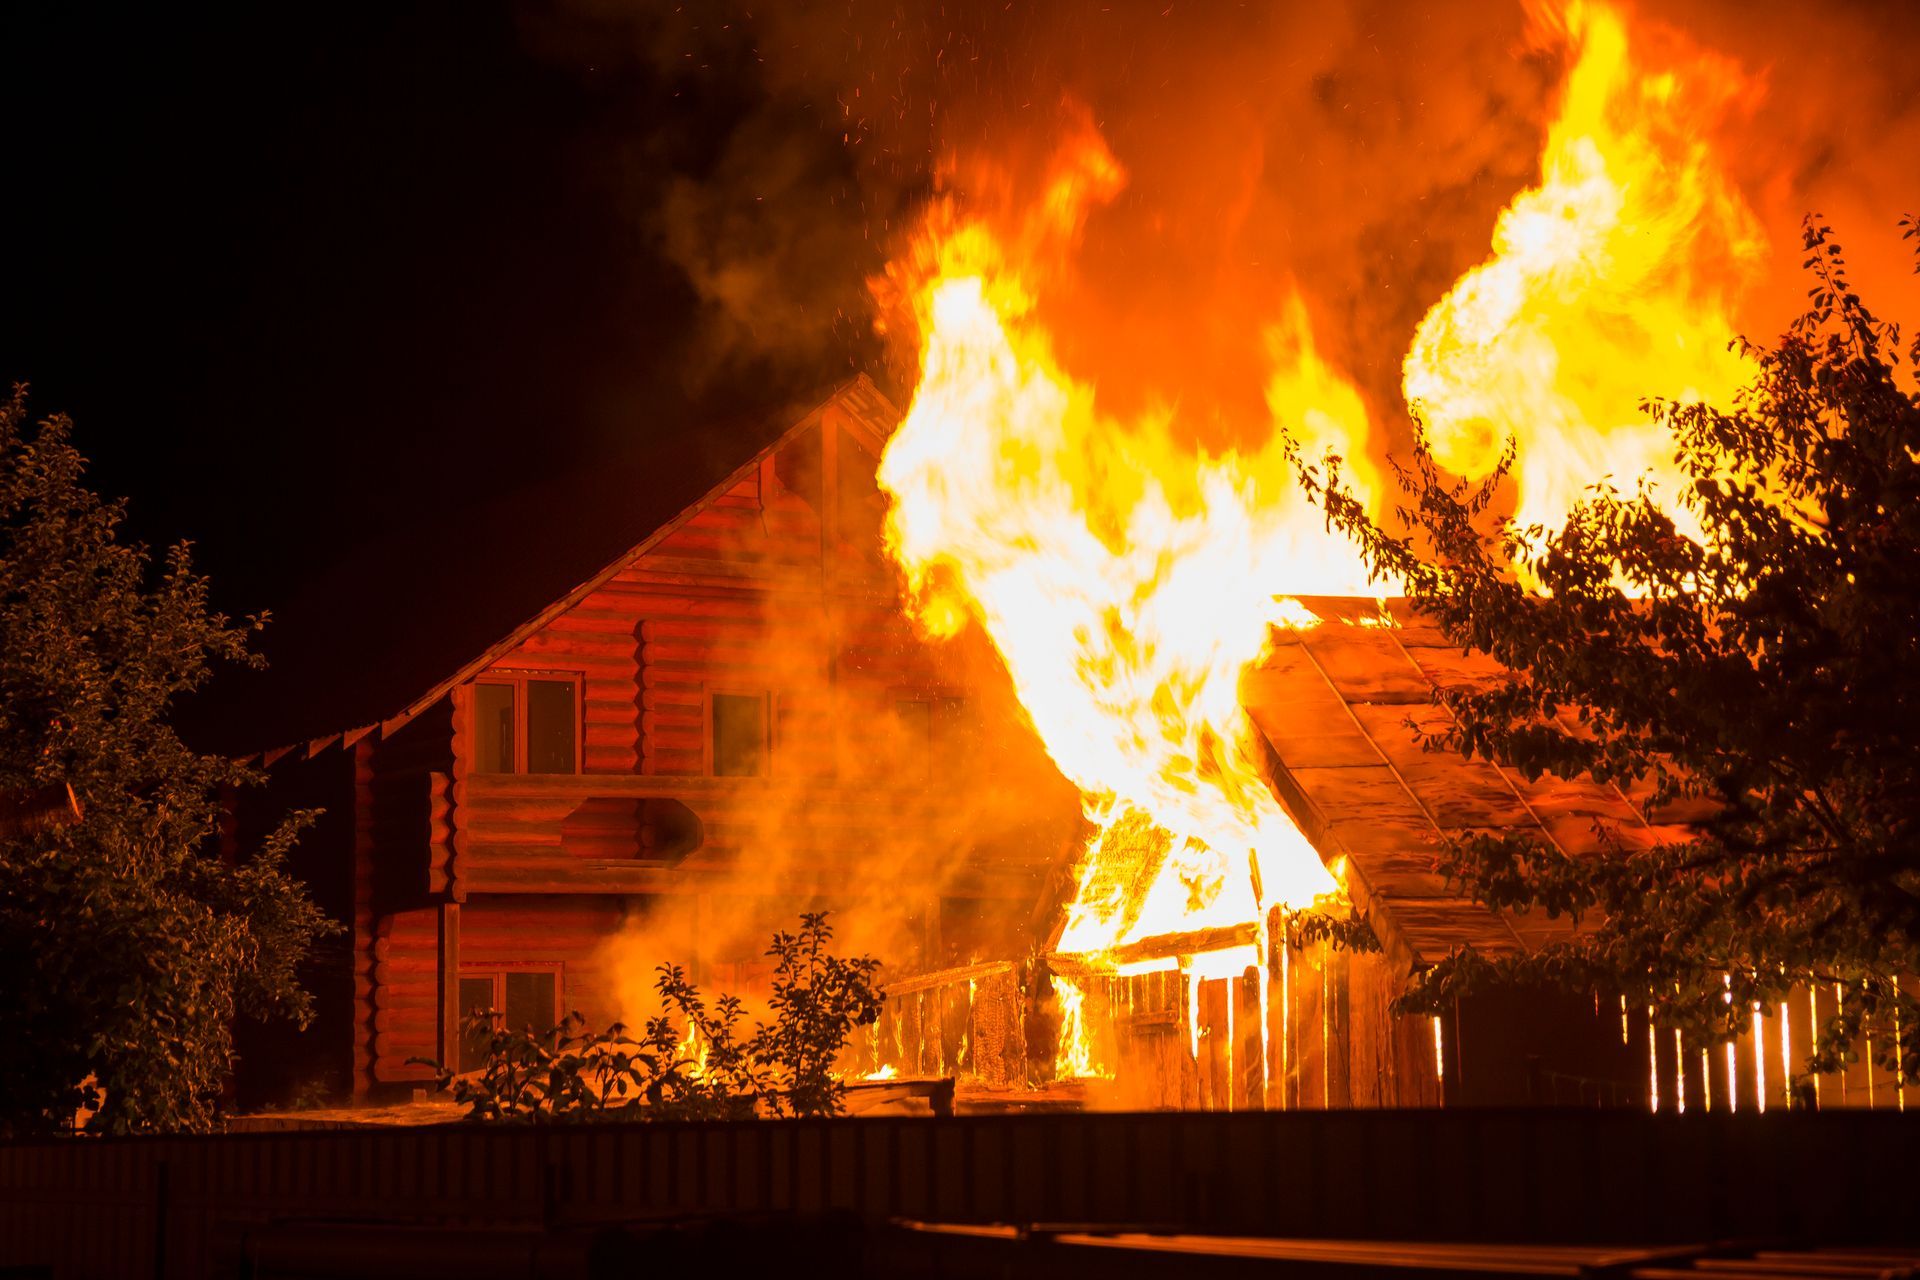
Smoke residue can spread far beyond the room where the fire started. Additional cleaning or repairs may be necessary after a more detailed inspection.
Incomplete Initial Documentation
Sometimes the original inspection simply doesn't capture every affected area. If new evidence becomes available, it may change how the damage is understood.
These are some of the situations that prompt homeowners to ask can a public adjuster reopen a closed insurance claim after the initial settlement.
What a Public Adjuster Can Do
A public adjuster cannot simply demand that an insurance company reopen a claim.
However, they may help by-
- Reviewing your insurance policy.
- Inspecting the property again.
- Identifying additional documented damage.
- Organizing supporting evidence.
- Preparing detailed estimates.
- Communicating with the insurance company.
- Explaining available claim options.
Their role is to represent the policyholder while evaluating whether additional action may be appropriate.
What You Should Do If New Damage Appears
If you discover damage after your claim has been closed, don't ignore it.
Instead-
Document Everything
Take clear photographs and videos before making repairs whenever possible.
Save Contractor Reports
If contractors discover hidden damage, ask for written documentation. Detailed repair reports can help explain what was found.
Keep Damaged Materials
If it's safe to do so, don't immediately throw away damaged materials. They may help demonstrate the extent of the loss.
Review Your Insurance Policy
Policies contain important language regarding supplemental claims, deadlines, and reporting requirements.
Contact TSO Adjustment Service
If you're unsure whether additional damage may still be considered, contact TSO Adjustment Service before contacting your insurance company. A public adjuster can review the situation and help clarify your available options.
This is one reason homeowners continue searching: can a public adjuster reopen a closed insurance claim after repairs begin.
Common Misunderstandings About Closed Claims
Many homeowners believe these statements are always true-
- "Once I cash the check, my claim is permanently over."
- "Hidden damage can never be reported."
- "The insurance company's first inspection is always final."
In reality, insurance claims depend on policy language, documentation, timelines and the specific facts surrounding the loss.
Assumptions can cause homeowners to miss opportunities to better understand their rights.
Why Waiting Too Long Can Make Things Harder
Even if additional review may be possible, delays can create challenges.
As time passes-
- Damage may change.
- Repairs may remove important evidence.
- Weather can make original damage harder to identify.
- Documentation becomes more difficult.
The sooner newly discovered damage is documented, the clearer the timeline becomes.
How TSO Adjustment Service Helps Homeowners
At TSO Adjustment Service, we understand that property damage doesn't always stop when the first inspection ends.
Our team works with homeowners to-
- Review insurance policies.
- Reinspect damaged property.
- Document newly discovered losses.
- Organize supporting evidence.
- Communicate with insurance companies.
- Help homeowners understand the next steps available under their policy.
Every claim deserves a careful review based on facts, not assumptions.
Final Thoughts
Discovering additional damage after receiving an insurance settlement can be frustrating, especially when you believed the claim was finished.
If you're asking can a public adjuster reopen a closed insurance claim, remember that there isn't one answer for every situation. The outcome depends on your policy, the reason the claim was closed, the evidence available and whether new covered damage has been identified.
Rather than assuming nothing can be done, it's worth having your situation reviewed so you understand what options may still be available.
If you need help evaluating your claim, TSO Adjustment Service is here to provide guidance based on your specific circumstances.
FAQs
Can a public adjuster reopen a closed insurance claim?
A public adjuster cannot automatically reopen every claim. However, they may review your policy, inspect newly discovered damage and help determine whether additional action may be possible based on your specific circumstances.
Can hidden damage be reported after a claim is closed?
Sometimes. If hidden damage is discovered during repairs, your options depend on your insurance policy, documentation and the facts surrounding the claim.
What if my contractor finds more damage after repairs begin?
Document the newly discovered damage immediately, request written reports from your contractor and review your insurance policy before assuming the claim cannot be revisited.
Is a supplemental insurance claim the same as reopening a claim?
Not always. A supplemental claim and reopening a claim can involve different processes depending on the insurer and the policy. Reviewing your policy details is important.
Should I contact a public adjuster before making more repairs?
If new damage is discovered, it's often helpful to document everything before additional repairs remove evidence. A public adjuster can review the situation and explain your available options.