Vandalism Claims Are Climbing Philadelphia's Premiums: So Why Do Insurers Fight Them Harder Than Storm Claims?
Philadelphia's property crime rate sits at roughly three times the Pennsylvania average, and that shows up directly in how often homeowners here file vandalism claims. Yet despite the volume, insurers push back on vandalism claims more than storm claims, mainly because proving intent is harder than pointing to a weather report.
A hailstorm doesn't need an alibi. It shows up in public records, on radar, in every local news report that night. Vandalism doesn't get that luxury. Someone smashes your window or spray-paints your fence, and suddenly you're the one who has to prove what happened, when it happened, and that you didn't cause it yourself. That imbalance is exactly why vandalism claims move differently than weather claims, and it's a bigger issue in Philadelphia than almost anywhere else in the state.
TSO Adjustment Service handles vandalism claims across the city regularly, and the pattern is consistent enough that we can usually predict where an insurer will push back before they even respond. Below is what filing looks like, and where these claims tend to get stuck.
So, how do I file a vandalism insurance claim? Start by addressing any immediate safety concerns and documenting the damage when it is safe to do so. Contact TSO Adjustment Service first for guidance on the claim process, and report the incident to the police when appropriate. You must also notify your insurer within the timeframe required by your policy. Contacting TSO should not delay a required report or any steps needed to prevent further damage.
What's the First Move After Discovering Vandalism?
Start by making sure the property is safe. If there is an immediate threat, an intruder, or a risk of injury, contact emergency services as appropriate. Once it is safe, photograph or record the damage before disturbing the affected areas, if possible.
Report suspected vandalism to the police when appropriate, and keep the report number and any related documentation. Then contact TSO Adjustment Service for guidance on documenting the damage and understanding the claim process.
Review your policy's notification requirements and notify your insurer within the required timeframe. Do not delay a required notification while waiting to speak with TSO or obtain a police report. If a broken window, damaged door, or another issue creates an immediate risk of further damage, take reasonable protective measures as soon as it is safe to do so. Keep receipts and photographs of the damage and any temporary repairs.
How Do I File a Vandalism Insurance Claim?
After addressing immediate safety concerns and contacting the police when appropriate, contact TSO Adjustment Service at 215-886-7440 for guidance on the claim process. TSO can help you understand what documentation may be relevant and what questions to consider when reviewing the damage and claim estimate.
You should also follow your policy's reporting requirements and notify your insurer within the applicable timeframe. Do not wait for a TSO appointment or review if your policy requires earlier notification.
Document the damage. Photograph and film the affected areas when safe, including wide shots that show the location and close-ups of individual items. If property was stolen or damaged, prepare an inventory and gather any available proof of ownership.
Keep repair estimates and receipts. Depending on the circumstances, estimates from qualified contractors may help you understand the cost of repairs. Before undertaking non-emergency repairs, document the damage and check any applicable policy requirements. Do not delay necessary temporary repairs to protect the property from further damage.
Keep copies of police records, correspondence, estimates, and receipts to support the claim review.
Why Weather Gets a Pass That Vandalism Doesn't
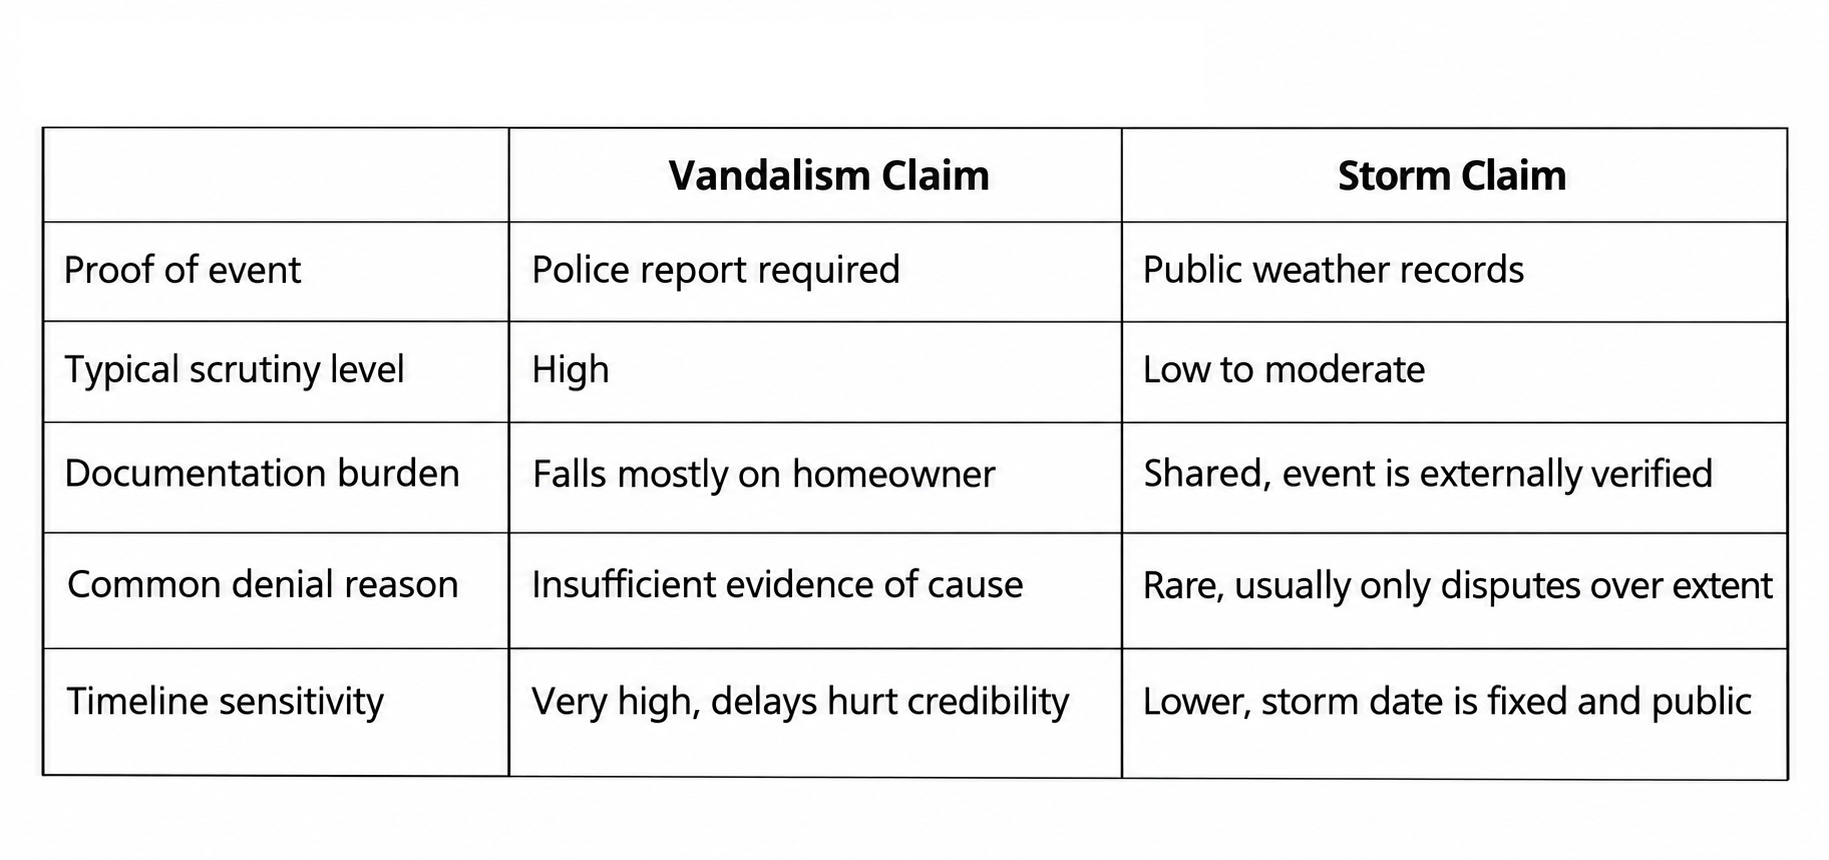
A storm is a shared, verifiable event. The National Weather Service confirms it happened. Every home in the path has the same story. There's nothing to argue about except the extent of the damage.
Vandalism is isolated and personal, which makes it inherently harder to verify. Was it really vandalism, or pre-existing damage you're now blaming on someone else? Did it happen when you say it did? Is the police report timestamp close enough to when you noticed the damage? These aren't questions insurers ask about hail. They're questions built specifically for claims where the only proof is your word plus whatever the police wrote down.
This is the core of why vandalism claims face more resistance. It's not that insurers think homeowners are lying. It's that the verification tools available for a criminal act are thinner than the tools available for a documented weather event, and insurers exploit that thinness by default.
The Documentation Gap That Trips People Up
Here's where a lot of Philadelphia claims fall apart, and it has nothing to do with the damage itself.
Someone experiences vandalism, gets upset, and handles it emotionally rather than procedurally. They clean up the glass before photographing it. They fix the fence before calling their insurer. They mention it to police almost as an afterthought, days later, once they've calmed down. Every one of those choices, made for completely understandable reasons, weakens the claim.
Compare that to a homeowner who, even while upset, calls police immediately, photographs everything before touching it, and contacts their insurer the same day. Same damage, same dollar amount, wildly different odds of a clean approval. The difference isn't the vandalism itself. It's the paper trail built around it.
Does Philadelphia's Crime Rate Actually Affect My Individual Claim?
Indirectly, yes. Insurers price risk by zip code, and areas with higher vandalism and theft rates get flagged for closer review across the board, not because any individual homeowner did anything wrong, but because the statistical pattern in that area invites more scrutiny.
Philadelphia's property crime rate running roughly three times the state average means insurers here have adjusted their internal review processes accordingly. That's part of why premiums climb in high-crime zip codes even for homeowners who've never filed a claim, and it's also part of why a legitimate vandalism claim from a Philadelphia address might get more questions than the identical claim filed from a quieter suburb.
When an Insurer Pushes Back Too Hard
Sometimes the scrutiny crosses from reasonable into excessive. If your insurer keeps requesting documentation you've already provided, drags out the timeline well past what similar claims typically take, or denies the claim citing "insufficient evidence" despite a solid police report and clear photos, that's worth challenging.
Request the denial or delay reason in writing. Compare it directly against what you submitted. If the insurer's reasoning does not appear to match the available documentation, contact TSO Adjustment Service to discuss whether an independent review may be appropriate. TSO can help assess the claim records, repair estimates, and policy provisions relevant to the dispute. Keep track of any appeal, response, or other deadlines that apply while seeking assistance.
Quick Reference: Vandalism vs Storm Claims
Frequently Asked Questions
Is a police report mandatory for a vandalism claim in Pennsylvania?
Most insurers require or strongly expect one. Without it, you're relying entirely on your own account, which significantly weakens the claim's credibility.
How do I file a vandalism insurance claim?
Within a few days at most. The longer the gap between discovery and reporting, the more an insurer can question whether the damage happened the way you describe.
Can an insurer deny my claim just because there were no witnesses?
Not automatically, but it makes the claim harder to support. A police report and thorough photo documentation can offset the lack of witnesses in most cases.
Will filing a vandalism claim raise my premium?
It can, particularly with repeated claims. That said, a single legitimate claim shouldn't outweigh the value of getting your damage properly covered.
What if the vandalism damage looks similar to normal wear and tear?
This is exactly where insurers push back hardest. Detailed, time-stamped photos and a police report describing the specific damage help separate the two clearly.
Should I get a second opinion if my claim gets denied?
Yes, especially if you have solid documentation and the denial still doesn't add up. An independent review can identify whether the insurer's reasoning actually applies to your case.
Need Help With a Vandalism Insurance Claim? Contact TSO First.
If your property has been damaged by suspected vandalism, contact TSO Adjustment Service at 215-886-7440 for guidance on the claim review process and the records that may help support your case.
When it is safe to do so, document the damage and report the incident to the police when appropriate. Contact TSO before contacting your insurer when practical, but do not delay any notification required by your policy. Take reasonable steps to protect your property from further damage and keep records of related expenses.
You can also contact TSO Adjustment Service online to discuss your property damage concerns.